Which Savings Goal Should You Fund First? A Simple Order for Families
Which Savings Goal Should You Fund First?
Most families save for several things at once: a safety net, a holiday, the next car, a house deposit, the kids' future. The usual approach is to put a little into everything. It feels fair, but it means every goal moves slowly, and the most important one, the safety net, is often the last to be ready.
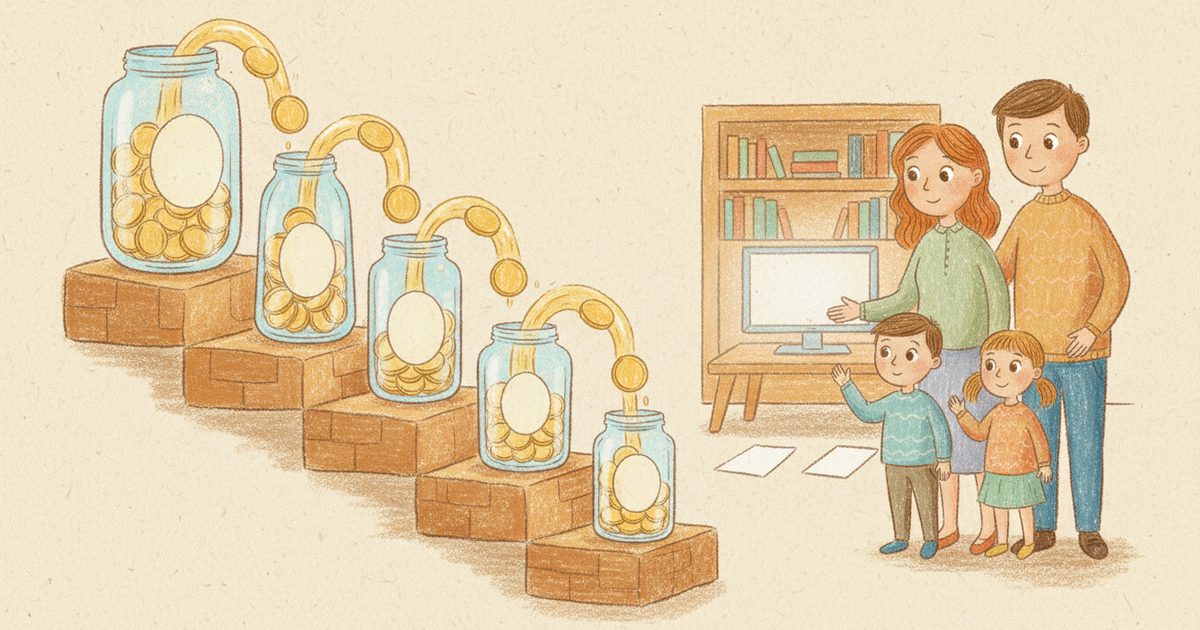
A better approach is to treat your goals as a queue. Money goes to the first goal until it's done, then the next, and so on. You agree on the order once, and every month there's nothing to debate.
A sensible default order
Every family is different, but this order works for most:
- Starter emergency fund. One month of essential costs. It stops a broken boiler from turning into credit card debt. See our emergency fund guide for families.
- Expensive debt. Credit cards and other high-interest debt. Paying it off is a guaranteed return. The loan overpayment calculator shows what extra payments save.
- Sinking funds for bills you know are coming. Insurance, car costs, holiday gifts. These aren't really "goals". They're bills paid in advance, so they come early. Use the sinking fund calculator for the monthly amount.
- Full emergency fund. Three to six months of essential costs.
- Tax-advantaged allowances. Retirement or savings accounts with a yearly limit, where unused room doesn't carry over.
- Medium-term goals. House deposit, next car, a big trip.
- Open-ended savings. "Just savings", with no target, which takes whatever is left.
You can change the order. Paying off debt before a full emergency fund is a classic debate. What matters is that you decide together once, rather than renegotiating every month.
How to split a surplus: the waterfall
When there's money left at the end of the month (a bonus, a tax refund, a good month), pour it down the queue:
- Fill the first goal up to what it still needs.
- Whatever's left goes to the second, up to what it still needs.
- Keep going until the money runs out.
- A goal with no ceiling, like open-ended savings, absorbs everything that reaches it. Put it last, or nothing gets past it.
An example
A family has a surplus of 1,500 and this queue:
| Order | Goal | Still needs |
|---|---|---|
| 1 | Emergency fund | 400 |
| 2 | Car sinking fund | 300 |
| 3 | Holiday | 2,000 |
| 4 | General savings | no ceiling |
The waterfall puts 400 into the emergency fund (now complete), 300 into the car fund (complete), and the remaining 800 into the holiday. General savings gets nothing this month, because the holiday still has room.
Goals with a yearly limit
Some pots have a ceiling that resets every January: a tax-free savings allowance, or "10,000 a year for holidays". For these, "still needs" means the room left this year. Once the year's limit is reached, the waterfall skips the goal until January, and the money flows on to the next one.
Doing it in FamilyJar
In FamilyJar, savings goals are a queue, not just a list:
- Move goals up or down the funding queue. The order is shared, so both partners see the same priorities.
- Targets and deadlines are optional. A pot can simply be savings.
- Yearly limits reset every January.
- Split a surplus: enter an amount and the app proposes how much goes to each goal down the queue. It's only a preview until you confirm the contributions.
- Valuations: if a pot earns interest or is invested, record what it's actually worth. The gain is tracked separately from what you paid in.
For more on setting goals together, read how to set and achieve family savings goals.
Frequently Asked Questions
Which savings goal should I fund first?+
For most families: a starter emergency fund, then high-interest debt, then sinking funds for known bills, then a full emergency fund, then yearly allowances and medium-term goals, with open-ended savings last.
Is it better to save for several goals at once or one at a time?+
Funding goals in order gets each one finished sooner and makes sure the most important ones, like the emergency fund, are ready first. Splitting money evenly feels fair but slows everything down.
How do I split extra money between savings goals?+
Use a waterfall: fill the first goal up to what it still needs, pass the rest to the next goal, and so on. A goal with no target should go last, because it absorbs everything that reaches it.
What about savings accounts with a yearly limit?+
Treat the room left this year as what the goal still needs. Once it's full, skip it until the limit resets and let the money flow to the next goal.
Written by
Rafał GawlikFounder of FamilyJar
Rafał Gawlik is the founder of FamilyJar, and a husband and father based in Kraków, Poland. He writes about family budgeting, the envelope method, and building financial security as a couple — drawing on the real-world workflows behind the FamilyJar app and his own experience running a household budget.
Related Articles
Sinking Fund Calculator: How Much to Save Each Month for Yearly Bills
Free sinking fund calculator. Add your yearly bills and goals, pick when each is due, and see how much to set aside every month, plus how much to catch up if you're starting today.
Best AI Budgeting Apps in 2026 — and How to Use AI Without Linking Your Bank
An honest look at the AI budgeting apps of 2026: Rocket Money, Cleo, Monarch, Copilot, Origin and Quicken Simplifi. What their AI does, what it costs, and your options if you don't want to connect your bank.
Best Budgeting Apps That Don't Require a Bank Login (2026)
Want to budget without handing over your bank login? These budgeting apps work without linking your accounts: FamilyJar, Goodbudget, EveryDollar, YNAB with manual accounts, Actual Budget and spreadsheets.